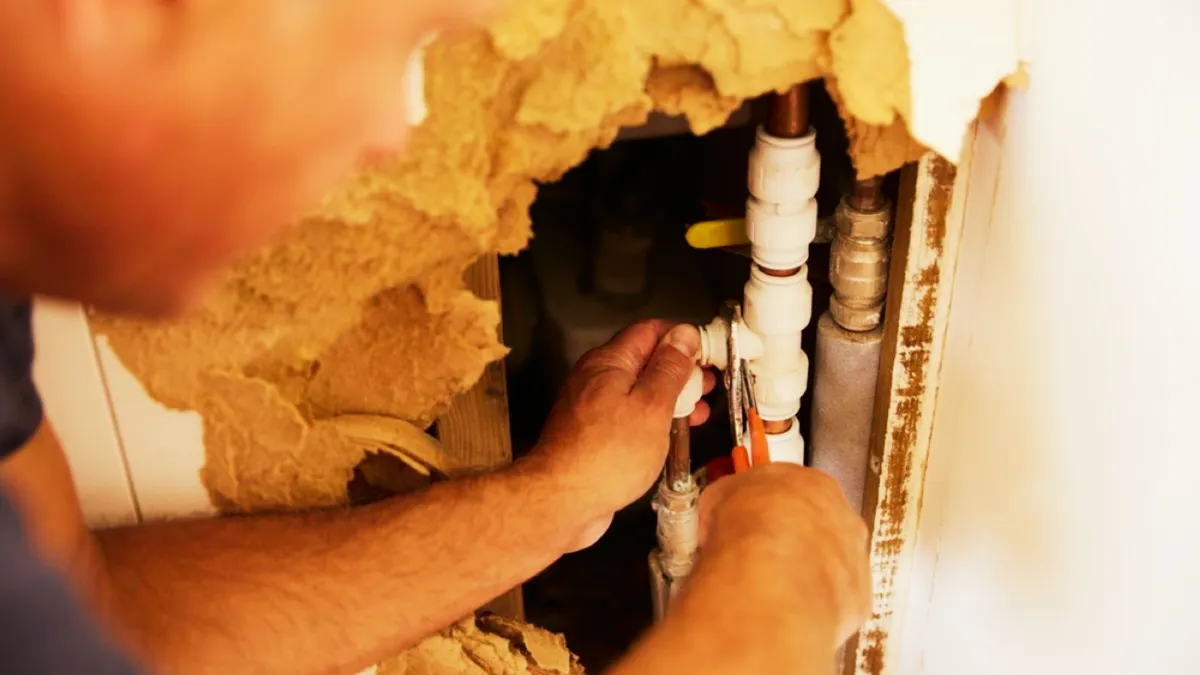
Texas policies generally cover sudden and accidental water damage, such as a burst supply line or a failed water heater. Gradual leaks, long-term seepage, and deferred maintenance are commonly excluded, which is why documenting the point of failure matters from the first hour.
Flood is a separate peril. Water entering from outside at ground level is excluded from standard homeowner policies and needs flood coverage, typically through the National Flood Insurance Program or a private flood carrier. Along the coast, wind-driven rain may fall under a Texas Windstorm Insurance Association policy instead.
Sewer backup is frequently its own endorsement with its own sublimit, separate from the main dwelling coverage. A great many property owners discover this only after a backup happens, so it is worth checking with your agent before you need it.
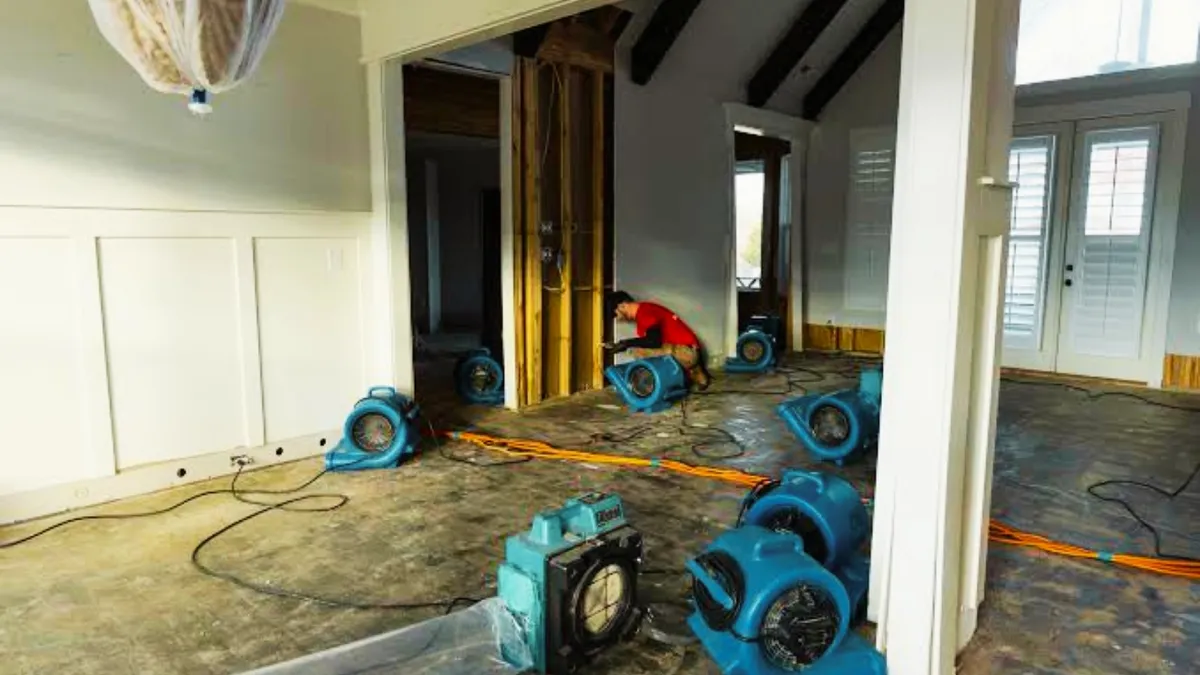
Most policies also obligate you to mitigate, meaning you are expected to take reasonable steps to limit further damage rather than waiting for an adjuster. Starting professional drying promptly usually supports a claim rather than jeopardizing it.